Figures below come from each company's public listings and 2026 third-party reviews (NerdWallet, MoneyLion's SoLo review, SuperMoney, app stores). Limits and fees change often — confirm in the app before relying on them. lenmeloans.com is not affiliated with any company named here.
Lenme vs SoLo Funds at a glance
| Criterion | Lenme | SoLo Funds |
|---|---|---|
| Model | P2P marketplace; investors set interest rates | P2P marketplace; borrowers offer optional tips to lenders |
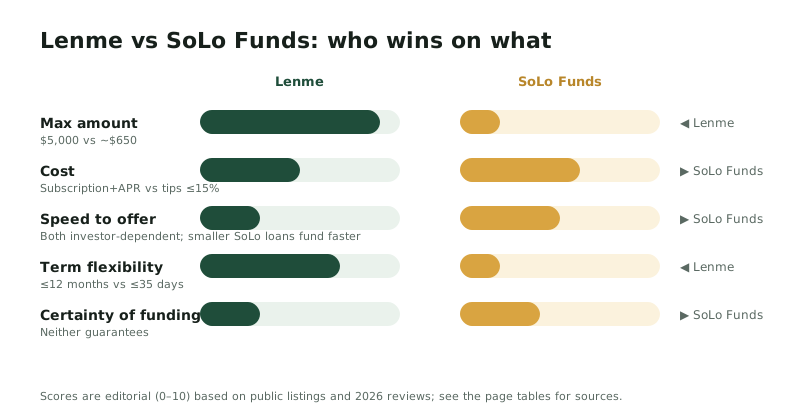
| Loan range | $50–$5,000; $200 cash advance; $10K crypto-backed | About $20–$650; first loan capped near $100 |
| Cost to borrower | Subscription (in-app) + investor APR (from 3%) + up to 1% origination | No mandatory fees; optional tip up to 15% of amount; 1.99% instant-transfer fee |
| Term | Up to 12 months | Up to 35 days, set by borrower |
| Credit check | No hard inquiry; investors see credit data | No traditional underwriting; uses SoLo Score from bank data |
| Time to an offer | Hours to weeks | Hours to days; not guaranteed |
| Deposit after funding | 1–2 business days | Few business days, or instant for 1.99% |
| Platform | iOS & Android app | iOS & Android app |
| Notable | Lenme Predict scoring; Automated Lending; Enterprise | Sued by CFPB in 2024 over tip disclosures; case dropped in 2025 |
Cost comparison on a $500 loan
On SoLo, a $500 loan with a 15% tip repaid in 35 days costs $75 — roughly a 156% APR equivalent if you annualize it, though SoLo presents it as a tip, not interest. On Lenme, a $500 loan at a 24% APR over 6 months costs about $35 in interest plus a $5 origination fee and the subscription (price shown in-app). Lenme is cheaper per dollar if you need months to repay; SoLo can be cheaper if you tip little and repay fast.
Where Lenme wins
- Much higher limits — $5,000 versus roughly $650.
- True installment structure with a stated APR and up to 12 months to repay.
- Crypto-backed loans and a $200 cash advance product.
- Investors can offer competitive rates to strong profiles.
Where SoLo Funds wins
- No subscription and no mandatory fees.
- Tiny first loans are easier to get funded than Lenme's requests.
- Simple 35-day structure for a paycheck gap.
- Longer track record in the U.S. P2P small-loan space.
The shared weakness: voluntary funding
Both apps leave you waiting for a person (or a person's automation) to pick your request. Reviews for both are full of 'nobody funded me.' If your need is time-sensitive, the honest advice is to run a parallel request through a lender network where review is automatic. Our form on this page does that in about 3 minutes with no fee.
Don't want to wait on either app?
Request $200–$5,000 from our lender network. Automatic review, answers in minutes.
Verdict
Lenme for larger, longer loans with a real APR; SoLo for very small, very short loans with no fees. For a guaranteed-fast answer, neither — use a lender network and compare the offer against both apps.
Frequently asked questions
Is SoLo Funds better than Lenme?
For small, short loans with no mandatory fees, SoLo Funds is simpler. For amounts up to $5,000 with a term up to 12 months, Lenme is the only one of the two that can do it.
Which funds faster, Lenme or SoLo?
Neither guarantees a timeline. SoLo's smaller requests tend to fund faster; Lenme's deposit after acceptance is 1–2 business days. SoLo charges 1.99% for instant transfer.
Do Lenme and SoLo check credit?
Lenme does no hard inquiry but shows credit data to investors; SoLo relies on its own SoLo Score built from bank and repayment history.
Can I use both apps?
Yes. Many borrowers keep both installed and request on whichever fits the amount they need.
Is there a no-wait alternative?
A lender-network request like the one on this page is reviewed automatically and usually answered in minutes.
Sources
Facts on this page were checked against the following sources on 2026-10-27. Links open in a new tab.