- Path 1: How a Lenme loan works
- Path 2: How our lender-network request works
- Side-by-side
- What happens after you submit to our network
- Estimate your payment first
- Tips to improve your odds on either path
- What happens to your request on each path, in detail
- Reading a loan offer in 60 seconds
- Security and privacy on both paths
- Timing, honestly compared
- After funding: managing the loan
- If you want to use both
- FAQ
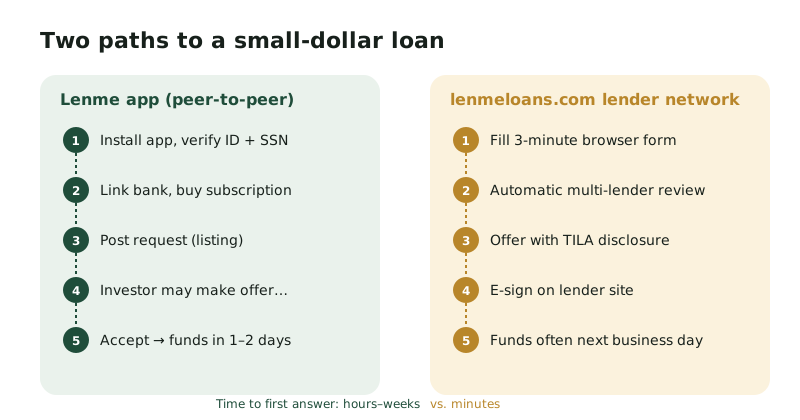
Path 1: How a Lenme loan works
Install & verify
Download Lenme from the App Store or Google Play, create an account, verify your identity with a government ID.
Link your bank
Connect your primary checking account. Lenme analyzes recent transactions and income for the risk profile investors see.
Post a request
Choose an amount ($50–$5,000) and a repayment period. No hard credit pull at this stage. A subscription is required.
Wait for offers
Investors browse requests and may send offers with their own interest rate. There is no guaranteed response time.
Accept & fund
Accept the offer you like. Lenme says funds reach your bank in 1–2 business days.
Repay via app
Automatic debits on your schedule; Lenme handles collection for the investor.
The weak point is step four. Lenme's marketing says 'offers in 30 minutes,' but because funding is voluntary, many first-time or thin-file borrowers wait days or never get an offer. That is the single most common complaint across the App Store, Trustpilot, and Reddit.
Path 2: How our lender-network request works
Fill out one form
About 3 minutes. Amount, contact details, income, and bank info. Nothing is shared until you submit.
Automatic lender review
Your request goes to lenders in our network. They evaluate it immediately — no waiting for a human investor to notice you.
See the offer
If a lender makes an offer, you're taken to their site to review the APR, fees, term, and payment schedule in full.
E-sign & receive funds
Accept by signing electronically. Many lenders deposit funds by the next business day.
lenmeloans.com is not a lender and does not make credit decisions. We pass your request to independent, third-party lenders. Each lender decides whether to make an offer and sets its own APR and terms. We never charge you for the request.
Side-by-side
| Criterion | Lenme app | Our request service |
|---|---|---|
| Where you apply | Mobile app only | Any browser |
| Account setup before an offer | Identity + bank linking + subscription | Form only; lender verifies after an offer |
| Who decides | Individual investors, one at a time | Multiple lenders, automatically |
| Typical time to an answer | Hours to weeks | Minutes |
| Guaranteed answer? | No — requests can expire | No guarantee of an offer, but you'll know quickly |
| Cost to request | Subscription required | Free |
| Amounts | $50–$5,000 (+$10K crypto) | $200–$5,000 |
| Funding after acceptance | 1–2 business days | Often next business day |
What happens after you submit to our network
Within seconds your request is matched against lender criteria such as state, income, and amount. If a lender is interested, you are redirected to that lender's website to finish the application — this is where any credit check happens and where you see the full Truth in Lending disclosure. If no lender makes an offer, you'll see that too, and you can try a smaller amount or a different product.
You are never obligated to accept. Reading the agreement matters: small-dollar loans can carry high APRs, and the lender's page will show the total cost, number of payments, and what happens if you pay late.
Estimate your payment first
Estimate only. Actual APR, fees, and terms are set by the lender you accept. Lenme investors set their own rates; our lender network sets theirs.
Ready to compare paths?
Submit a request to our lender network now. It's free and takes about 3 minutes.
Tips to improve your odds on either path
- Request only what you need — smaller requests are funded more often on Lenme and approved more often by lenders.
- Make sure your bank account shows regular income deposits and no recent overdrafts.
- Use your legal name and current address so identity verification passes the first time.
- On Lenme, watch the feed to see what rates are being funded and price your request accordingly.
- Never pay an upfront 'processing fee' to anyone promising a guaranteed loan — legitimate lenders deduct fees from proceeds or add them to the balance.
What happens to your request on each path, in detail
On Lenme: a request is a listing
Your Lenme request behaves like a listing in a marketplace. It has an amount, a term, and a rate you'd accept, plus a profile investors can inspect: Lenme Predict score, credit band, banking summary, and your Lenme history. Investors (or their Automated Lending rules) decide whether to make an offer. Several may; none may. Lenme does not top up, guarantee, or expedite listings. When you accept an offer, Lenme becomes the servicer: it collects payments and passes them to the investor.
Through our network: a request is an application
Your request to lenmeloans.com is treated as an application distributed to lenders in our network whose criteria you match — state, amount, income type, and so on. Lenders run their own underwriting, which may include a soft inquiry to pre-qualify and a hard inquiry if you continue. If a lender wants to offer, you're redirected to its site to see the full Truth in Lending disclosure and e-sign. We never see or influence the rate; we're paid a referral fee by the lender, which is disclosed on our disclosures page.
Reading a loan offer in 60 seconds
Whichever path you take, the agreement you sign is governed by the federal Truth in Lending Act (Regulation Z), which requires the lender to show four numbers in a standard box:
| TILA term | What it means | What to compare |
|---|---|---|
| APR | Yearly cost including interest and most fees | Lower is cheaper for the same term |
| Finance charge | Total dollars the loan costs you | The honest 'price tag' |
| Amount financed | What you actually receive (after fees deducted up front) | May be less than the 'loan amount' |
| Total of payments | Everything you'll pay back | Finance charge + amount financed |
Also look for: the payment schedule, late and returned-payment fees, whether there's a prepayment penalty, whether the loan is reported to credit bureaus, and how to contact the lender. On Lenme, the equivalent information appears in the offer and loan agreement inside the app.
Security and privacy on both paths
- Encryption: Lenme's app and our request form both use TLS; our form is served over HTTPS with HSTS enabled.
- What's collected: Lenme collects SSN, ID, location, and bank transaction history up front. Our form collects identity, income, and bank details needed by lenders; lenders verify after making an offer.
- Who sees it: On Lenme, investors see a profile (not your raw documents). Through our network, lenders who match your request receive it; we don't sell it to unrelated marketers, and you can opt out of sharing on our privacy choices page.
- Red flags on any path: upfront fees, pressure to pay by gift card or wire, or anyone asking for your Lenme or bank password. The FTC's advance-fee loan guidance applies everywhere.
Timing, honestly compared
| Milestone | Lenme (per Lenme / reviewers) | Our network (typical) |
|---|---|---|
| Request submitted | 5 minutes after verification | About 3 minutes |
| First response | 30 minutes best case; days to weeks common | Minutes |
| Decision | When an investor chooses you | Lender decision usually same session |
| Funds in account | 1–2 business days (Finder: 1–3) | Often next business day after e-sign |
After funding: managing the loan
Set a calendar reminder two days before each payment, keep the funds in the account the lender debits, and contact the lender before a payment fails if you're short — most will reschedule once, and a returned payment costs more than a reschedule. If you borrowed on Lenme, the same advice applies, with Lenme as the servicer. Paying off early is sensible on our network's installment products (check for a penalty first) and may carry a prepayment fee on Lenme.
If you want to use both
There's no rule against posting a Lenme request and submitting here on the same day. Accept only one loan. Don't stack two loans due on the same payday — that's the most common way a $500 shortfall becomes a $1,500 problem by next month.
Frequently asked questions
Does lenmeloans.com send my request to Lenme?
No. We are not connected to Lenme Inc. Your request goes to our own network of third-party lenders. If you want a Lenme loan, use the official Lenme app.
Do I have to accept an offer?
No. Both on Lenme and through our network you can decline any offer. Only sign if the APR, fees, and payments fit your budget.
Will requesting hurt my credit?
Posting a Lenme request does not involve a hard inquiry. Lenders in our network may perform a soft inquiry to pre-qualify and a hard inquiry if you proceed with a loan — the lender will tell you before it happens.
How fast can I get money?
On Lenme, 1–2 business days after an offer is accepted, but offers can take days. Through our network, lenders often fund by the next business day after you e-sign.
Is there any fee to use this site?
No. Our request form is free. Any cost comes from the loan agreement you choose to sign with a lender, and it is disclosed before you sign.
What is a Truth in Lending disclosure?
A federally required box showing APR, finance charge, amount financed, and total of payments before you sign. Lenders in our network must provide it; Lenme shows equivalent terms in-app.
Does lenmeloans.com see my rate or decide it?
No. The lender sets the rate and terms and shows them to you directly. We receive a referral fee from the lender, disclosed on our disclosures page.
Can I cancel after e-signing?
Some lenders allow rescission within a short window; many do not once funds are sent. Read the cancellation terms before signing, and never sign to 'see the numbers' — the numbers are shown before signing.
Sources
Facts on this page were checked against the following sources on 2026-10-27. Links open in a new tab.